
Yesterday's signals, distilled, A look back at October 11, 2026.
Apple put the home back on the calendar.
Anthropic’s infrastructure sprint got priced like a utility business.
And the data center buildout ran into its real constraint set: permitting, disclosure, and the politics of power and water.
Underneath the headlines is a structural convergence: AI is becoming physical infrastructure and ambient interface at the same time.
That combination changes who has leverage. The grid operator and the zoning board start to matter as much as the GPU vendor. The living room screen becomes a distribution surface that can be governed, monetized, and instrumented. And “trust” stops being a brand attribute and becomes a permitting input.
The strategic question for operators is simple: where are you still planning like compute is elastic and interfaces are personal, when the stack is moving toward constrained infrastructure and shared surfaces?
INFRASTRUCTURE / COMPUTE
Power-secured sites are now an asset class, and the public is part of the cap table
Anthropic data center leases get modeled like a revenue utility
Analysts estimated a 245 MW AI data center site could yield roughly $1.3B per month in revenue, alongside reporting that Anthropic signed a cloud deal with IREN, per The Information.
The important detail isn’t the exact model output. It’s that the market is now comfortable valuing AI capacity as a monetizable, power-anchored throughput business.
The Bet: If you can secure power and interconnect, demand will be there at a price that supports long-duration leases and heavy capex.
So What? This is compute’s shift from “IT supply chain” to “infrastructure finance.” When a single site is discussed in monthly revenue terms, the negotiation center moves to power contracts, land, and interconnect rights, not just chips and model quality. For large buyers, it also means your unit economics will increasingly reflect local constraints, grid upgrades, cooling, and permitting, rather than global cloud abstraction.
The Risk: These revenue models assume sustained high utilization and pricing power. If model efficiency, demand cyclicality, or regulatory constraints soften utilization, the same fixed-cost structure becomes a balance-sheet stressor.
Action:
- Map your AI roadmap to a power reality, ask your cloud and colo partners what MW they can actually deliver in your target regions over the next 6–18 months.
- Add “capacity provenance” to vendor diligence, where the power comes from, what the interconnect looks like, and what permitting dependencies exist.
- Stress-test your product margins against a step-function increase in inference cost tied to regional capacity scarcity.

INFRASTRUCTURE / PERMITTING
Data center opponents push for transparency as NDAs become a liability
Local resistance to data centers is being amplified by secrecy, NDAs around power, water, and emissions data are feeding distrust and slowing approvals, per TechCrunch.
This isn’t a moral argument. It’s a timeline argument.
So What? The permitting path is becoming a product constraint. If your growth plan assumes “we’ll just add capacity,” you’re implicitly assuming communities will accept opaque projects that change local power pricing, water usage, and land use. Operators should treat disclosure strategy as part of infrastructure execution, because the fastest way to miss a launch window is to discover you don’t have a credible public narrative for your load.
The Risk: Over-disclosure can create competitive exposure and invite politicized interpretation of partial data. The wrong transparency posture can be as damaging as secrecy.
Action:
- Build a disclosure packet now, power draw, water plan, noise/heat mitigation, and local economic impact, before you need it.
- Put permitting lead times into your capacity planning model, assume delays, not best-case.
- Ask infra partners directly what they will and won’t disclose publicly, then decide if that posture is compatible with your siting strategy.
PLATFORMS / HOME SURFACES
Apple is rebuilding the home as a governed interface layer
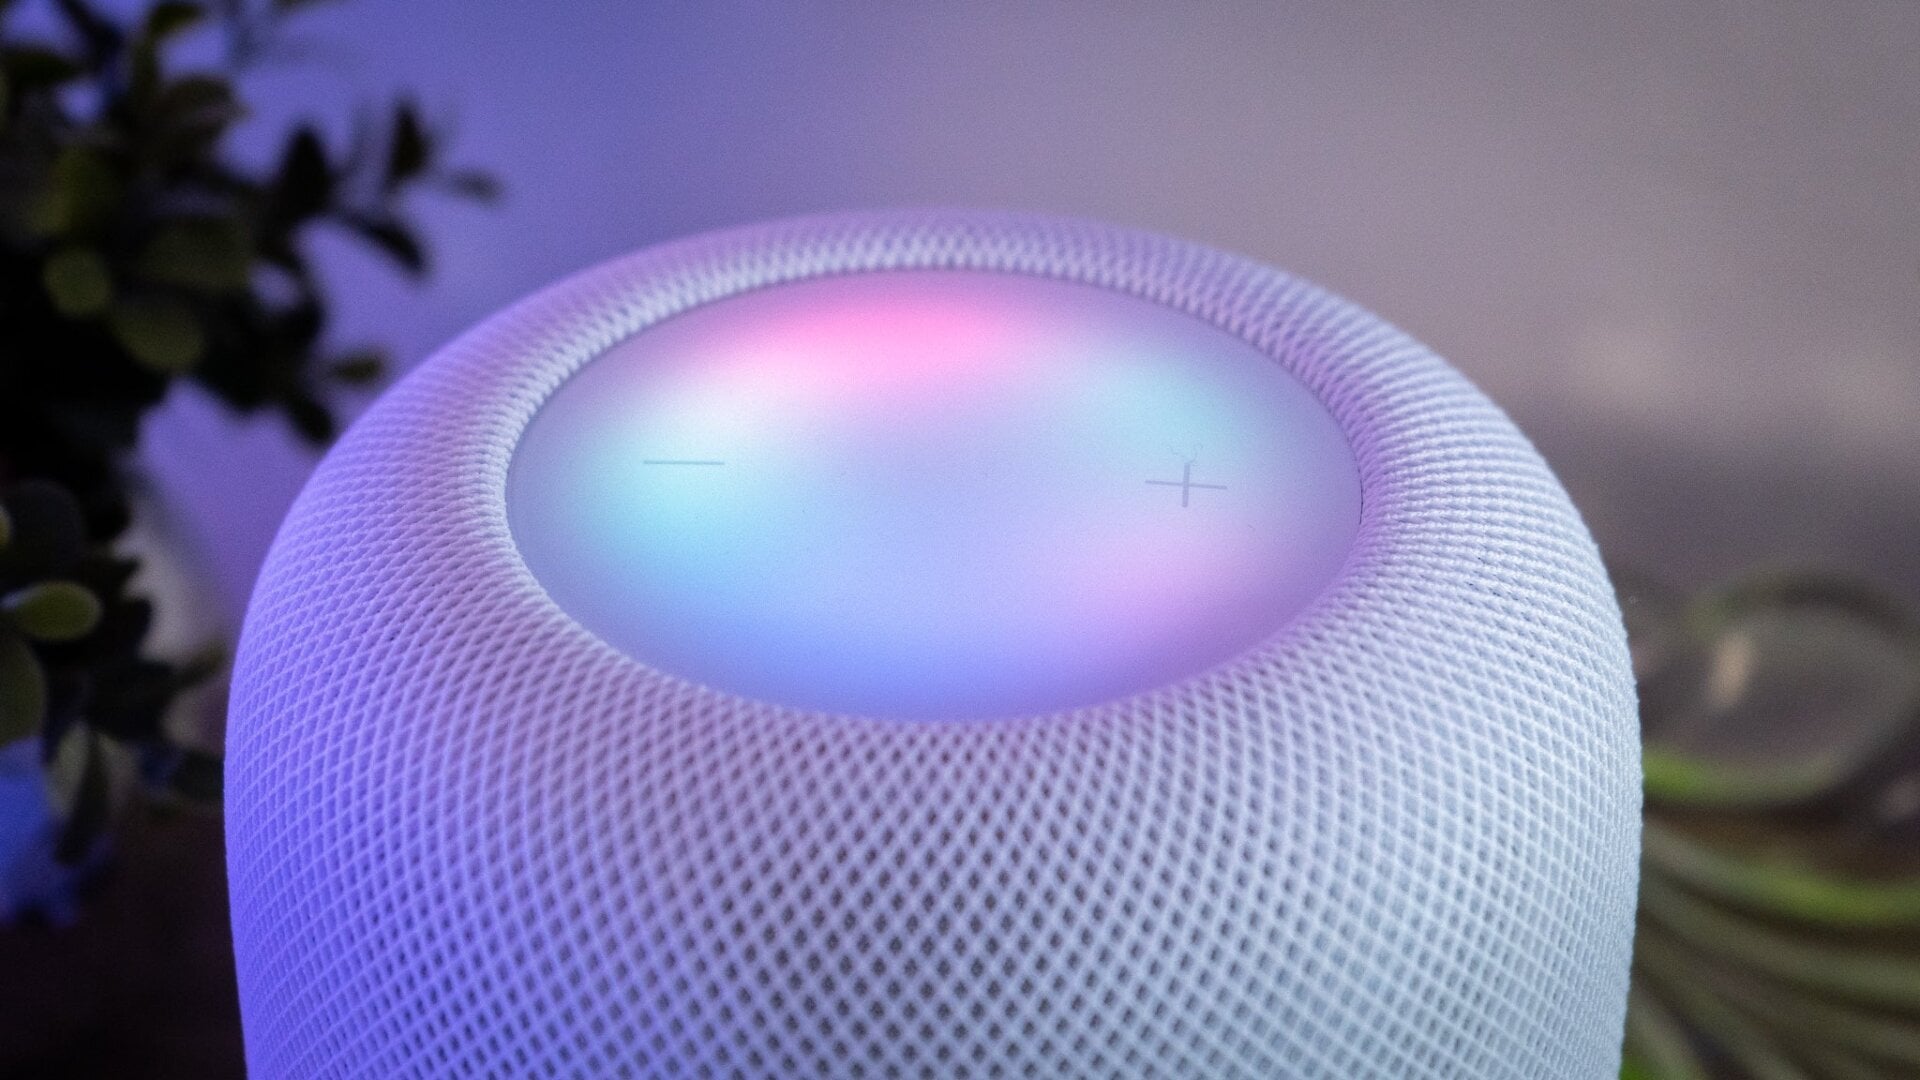
Apple’s HomeView hub and smart home push re-center the living room screen
Reporting points to Apple’s smart home strategy centering on a HomeView display hub, alongside a new HomePod mini, Apple TV updates, and second-party accessories from LG and Schneider, per Bloomberg.
This is Apple treating the home like an OS problem, identity, permissions, device orchestration, and default surfaces.
The Bet: The next consumer control point is ambient, persistent screens and speakers that mediate household intent, not just phone apps.
So What? If HomeView lands, it creates a high-usage, high-trust endpoint where Apple can enforce policy, shape commerce flows, and standardize “assistant-adjacent” interactions. For consumer operators, this is less about a new gadget and more about a new distribution gate. The winners won’t be the loudest assistants. They’ll be the services that integrate cleanly into Apple’s home permissioning model and show up at the right moment, without feeling like an app.
The Risk: Smart home history is littered with false starts, interoperability friction, unclear consumer value, and slow accessory adoption. A hub alone doesn’t guarantee daily engagement.
Action:
- Audit your product for “ambient fit”, what does your core workflow look like on a shared household screen with multiple identities.
- Revisit HomeKit integration and certification dependencies, assume premium Apple households will expect first-party-grade behavior.
- Decide what you will not build, if Apple owns the orchestration layer, competing at the control plane is usually wasted motion.
CAPITAL FLOWS / ROBOTICS
Physical AI capital is chasing data rights, not just robots
PitchBook: physical AI raises hit ~$48B YTD as companies gather task data in real environments
Robotics and physical AI companies have raised roughly $48B year-to-date, with an emphasis on gathering training data from people completing tasks in factories, offices, and homes, per Financial Times.
The money is following the dataset.
So What? The next negotiation for many operators won’t be “should we buy robots.” It will be “what are our terms for data capture in our facilities.” If training advantage comes from observing real task completion, then factories and offices become upstream data suppliers, whether they intended to or not. That creates a new category of enterprise leverage: you can trade access for pricing, liability terms, on-prem constraints, or revenue share.
The Risk: Data collection in workplaces and homes is a governance minefield, privacy, labor relations, IP leakage, and security exposure. The fastest path to a pilot is often the slowest path to durable deployment if you don’t set terms early.
Action:
- Write your data access position this week, what can be captured, retained, exported, and used for training, and under what compensation and audit rights.
- Add “dataset externalities” to procurement, treat cameras and telemetry like a data-sharing contract, not a hardware line item.
- Identify the workflows where you would pay for automation but refuse data export, then design for on-prem or constrained logging from day one.
CONTRARIAN SIGNAL
Transparency is becoming a capacity primitive
The default read on data center transparency is reputational: be nicer to communities, reduce backlash, move faster.
The deeper mechanism is that disclosure is turning into a throughput enabler. When power is scarce and permitting is contested, the projects that ship are the ones that can survive public scrutiny with credible numbers and enforceable mitigations. NDAs don’t just hide competitive details, they slow the only process that matters: getting electrons to racks on time.
The same pattern shows up at the consumer edge. If Apple is serious about HomeView, it’s not just adding a screen. It’s adding a governed surface where identity, permissions, and provenance can be enforced by default. That’s “transparency,” too, just implemented as platform control rather than public disclosure.
The Takeaway: The next phase of AI scale rewards operators who can prove what they’re doing, either to a zoning board or to a platform permission layer.
THE QUESTION FOR TODAY
Power is now a roadmap constraint. Permitting is now a schedule constraint. Ambient surfaces are becoming distribution constraints. And physical AI is turning your workplace into a dataset negotiation.
Where are you still operating as if scale is just a procurement problem, not a disclosure-and-permissions problem?
Signal + Noise is strategic intelligence, not engagement-specific advice. For guidance calibrated to your org, start with Advisory.
See exactly how this impacts your specific industry and function. Upgrade to PRO to get bespoke tactical breakdowns generated instantly for your operating model.
Go deeper with the Weekly Signal
This is the daily take. The Weekly goes further — full strategic analysis across 8–10 sections, each with a signal read and operator action items. Source panel included.
Sign up free → then upgrade