Last week's signals, distilled, A look back at Oct 31–Nov 6, 2026.
By Isaiah Steinfeld, AI, Venture Innovation & Technology Strategy
The Arc: Permissioning Becomes the Control Plane The week didn’t hinge on a single model jump. It exposed a more operational constraint: AI scale is now negotiated, not assumed. Permits, grid interconnect, community tolerance, import approvals, platform defaults, and internal spend controls all showed up as gating functions. Capital is still flooding the frontier. But capital is no longer the scarce input. Permission is.
That changes what “execution” means. The winning posture is less about picking the best model and more about building a portfolio of options across compute, vendors, regions, and interfaces, then instrumenting cost and risk so you can steer when constraints tighten. The practical question for a leadership meeting this week: where are we still planning as if access to compute, chips, and user data is frictionless, and who owns the fallback when it isn’t?
INFRASTRUCTURE & POWER
Compute delivery is being re-architected around permits, grids, and social license, not just GPUs.
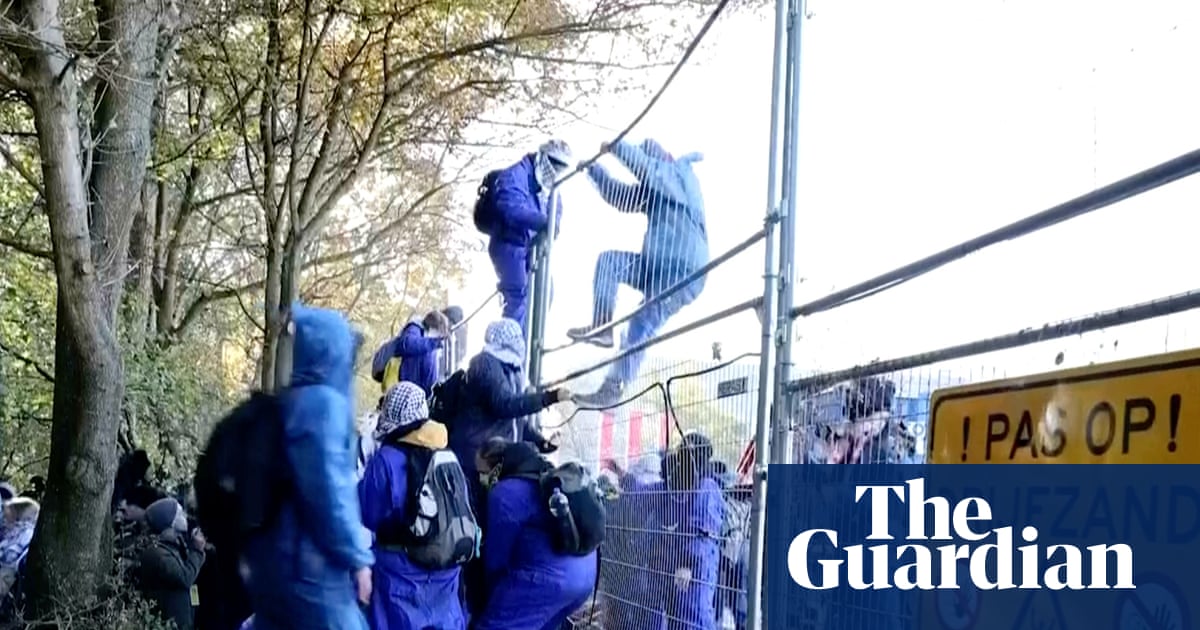
• OpenAI, launched “Grid Protectors” tied to its Georgia campus, committing up to 1,000 MW of flexible demand, per The Verge • Nvidia / Apollo, explored retrofitting 130+ legacy telecom buildings into small data centers as a workaround to hyperscale backlash, per The Information • Meta, warned new US data center builds get harder post-midterms while expansions get easier, per The Wall Street Journal • Microsoft, saw activists breach a data center construction site in Amsterdam, turning “opposition” into schedule and security risk, per The Guardian • Google, argued space data centers can cost up to 100x more than Earth-based and that permitting is the bottleneck, per The Information
Signal: The capacity race is shifting from “who can buy chips” to “who can reliably earn and keep permission to energize and operate sites.” Action: Ask providers to map your contracted SKUs to specific campuses and expansion milestones, then build a 90-day and 180-day delay plan for incremental capacity.
CAPITAL FLOWS & FRONTIER BALANCE SHEETS
Frontier labs are being financed like sovereign-scale infrastructure counterparties.
• OpenAI, reportedly closed roughly $11B at a $1.25T valuation, with up to $20B total in play, per Bloomberg • Anthropic, reportedly still aiming to list before Thanksgiving, targeting $80B–$100B raised at a $1.25T–$1.75T valuation, per Financial Times • Thinking Machines Lab, reportedly closing in on a $5B round at a $40B valuation, per Business Insider • Crunchbase, flagged that AI, defense, and space tech led the week’s biggest rounds, including Shield AI’s $2B raise, per Crunchbase News
Signal: The market is pre-financing frontier capability as a durable asset class, while the physical layer remains the gating function. Action: Treat frontier vendors as long-lived dependencies, write exit ramps, version pinning, and data/log export into renewals before usage becomes “too big to move.”
SEMICONDUCTORS, MEMORY, AND SOVEREIGNTY
The bottleneck is broadening from accelerators to memory, optics, and cross-border approvals.
• TSMC, reportedly considering manufacturing 3D DRAM at Nvidia’s request amid shortages, per The Information • YMTC, targeting 70% local equipment sourcing for its fourth fab, up from just over 50% for its third, per Reuters • Nvidia, ~600,000 H200s reportedly stored in Hong Kong awaiting China import approval, per Reuters • SK Hynix, US approval reportedly held up for chipmaking equipment tied to China expansion, complicating New York plans, per Reuters • Marvell, agreed to buy Lumentum in a $115B all-stock deal, consolidating optics as an AI data center control point, per Reuters
Signal: “Compute availability” is now a system-level supply chain question, memory, optics, packaging, and border policy can all throttle throughput. Action: Update your capacity plan to include memory and interconnect assumptions, then ask providers how they’re securing those components, not just GPUs.
PLATFORMS & DEFAULT SURFACES
AI is becoming a condition of access on core surfaces, opt-out is getting more expensive.
• Google, said schools can restrict Gemini but cannot remove AI from Search without losing Search access, per The New York Times • Apple, opened Siri AI to every app with usage limits and a coming fee for expanded use, per The Next Web • Apple, brought Apple Intelligence to China with an Alibaba-powered content filter while adding always-listening watch features, per Bloomberg
Signal: The interface layer is turning AI into policy, defaults, bundling, and metering will shape adoption more than internal enthusiasm. Action: Inventory which “default surfaces” you cannot replace (Search, OS, browser, endpoint), then write an “AI-on by default” governance stance instead of debating toggles you may not control.
ENTERPRISE FINOPS & INTERNAL GOVERNANCE
Once AI spend is measurable, it becomes contestable, and adoption becomes a finance workflow.
• Apple, cut some engineers’ daily AI spending cap to $200 from $300, with plans to go lower, per Bloomberg • Anthropic, introduced Smart Reports to flag usage costs and inefficiencies, per Business Insider
Signal: AI inside the enterprise is moving from “tooling” to “metered utility”, and the control plane is shifting toward reporting, quotas, and chargebacks. Action: Instrument usage by workflow and outcome this week, then set a lightweight review gate for high-cost agentic runs before finance does it for you.
GOVERNANCE, LIABILITY, AND NATIONAL SECURITY
Regulation is moving from principles to enforcement posture, plus influence and espionage risk at the top of the stack.
• OpenAI, planned a post-midterms push for mandatory “speed limits” and “AI compute campuses” framing, per Axios • California, elected State Senator Scott Wiener (author of SB 53) to Congress campaigning on AI regulation, per The Information • UK NCSC, said China and Russia are expected to routinely use AI-enabled cyber operations by 2028, per Financial Times • US House chairs, asked Nvidia’s Jensen Huang to explain a reported spy link, per The Next Web • Reporting, said the alleged spy targeting Huang worked directly for China’s top spy agency, per Gizmodo AI
Signal: “AI governance” is becoming inseparable from security governance, capability thresholds, executive influence risk, and cyber volume are converging into one board-level surface. Action: Treat executive comms/travel hygiene and vendor dependency as part of your AI risk register, then rehearse a response plan for policy-driven access changes (model tiers, regions, or licensing).
MARKET STRUCTURE: NEOCLOUDS, BACKSTOPS, AND REAL BALANCE SHEETS
The compute middle layer is entering a credibility test, thinly capitalized capacity will get repriced.
• Neoclouds, faced a financial reckoning as Nvidia weighed how far to help backstop them, per Business Insider
Signal: The market is re-learning that “cheap capacity” can be a counterparty risk, especially when the upstream supplier becomes the lender of last resort. Action: If you rely on a neocloud, map your exit path now, data egress, model portability, and reserved capacity transfer terms, before a shakeout forces your hand.
ASSISTANTS IN REGULATED SURFACES
Assistants are entering high-liability domains through read-only footholds, trust before execution.
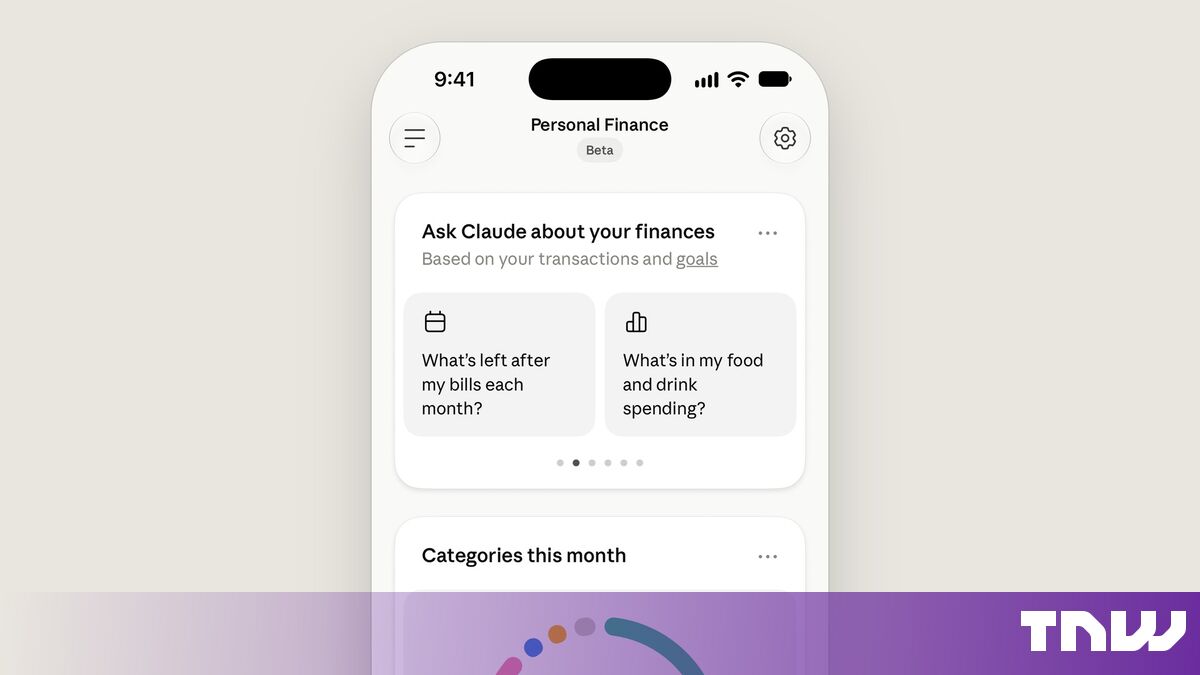
• Anthropic, launched a Claude Personal Finance beta using read-only Plaid access, per The Next Web • Kalepa, raised a $75M Series B at a $470M valuation for AI underwriting/pricing/portfolio management, per Reuters
Signal: The adoption wedge in regulated domains is “insight with auditability,” not autonomous action, execution will arrive only when liability frameworks are ready. Action: Ship read-only connectors with least-privilege scopes and full audit trails, then decide explicitly what would have to be true to grant write access.
CAPABILITY & WORK: CODING AGENTS AND MODEL TIERS
The work surface is shifting from single copilots to orchestrated agent swarms, and the model layer is segmenting by cost/latency.
• Meta, acquired Conductor, whose app runs AI coding agents in parallel, per The Next Web • Google DeepMind, released Gemini Omni 1.2 Flash positioned as faster and more cost-effective with longer clips, per Google DeepMind Blog • OpenAI, announced it will acquire Pierre Computer Company, Inc., per OpenAI News
Signal: The next productivity step is orchestration, multiple agents, parallelism, and review discipline, paired with cheaper tiers that make high-volume multimodal workloads viable. Action: Define your “agent integration pattern” (review gates, test harnesses, merge discipline) before you scale parallel agents, and re-run unit economics against new fast/cheap tiers.
CONTRARIAN SIGNAL
The constraint isn’t model access. It’s delivery certainty.
• OpenAI can raise $11B at a $1.25T valuation, per Bloomberg • A Microsoft site can still get physically disrupted, per The Guardian
Signal: Capital can buy talent and contracts. It cannot automatically buy permits, grid interconnect, or community tolerance on your timeline. Action: Stop treating compute as a purely financial input, add “permissioning risk” to roadmap planning the same way you add security and uptime risk.
WHERE TO START THIS WEEK
Three moves with the highest leverage given the week's signals. Pick one, none of these reward half-attention.
-
Map your permissioning exposure. Build a one-page dependency map from product SLAs to physical reality: which regions, which campuses, which expansion milestones, which permitting climates. If a 180-day delay hits your primary provider’s next build, which launch slips first, and what do you ship instead.
-
Turn AI spend into an operating metric, not a surprise. Instrument token and tool-call usage by workflow and outcome, then set a weekly review for the top 10 cost drivers. If finance cut your model budget by 30% tomorrow, which workflows would you protect, and can you justify them with evidence.
-
Design for conditional access. Assume at least one of these becomes constrained: a region, a model tier, a connector, or a platform surface. Implement version pinning, provider bake-offs for top workloads, and a degraded-mode plan for your AI features. If a vendor changes terms or access, can you keep the product stable for 30 days without heroics.
THE QUESTION
Compute is being treated like contested infrastructure. Platforms are bundling AI into default surfaces and charging for the privilege. Supply chains are splitting along sovereignty lines while memory and optics become bottlenecks. Enterprise AI is becoming measurable, then rationed.
Where is your AI strategy still assuming unconditional access, and what is the first decision you’ll make when access becomes conditional?
THE WEEK AHEAD
What to watch:
• Anthropic IPO path, Watch for concrete filing mechanics, governance posture, and enterprise contracting signals if the “before Thanksgiving” plan holds, per Financial Times • US data center permitting climate, Watch for early post-election moves that distinguish “new site” hostility from “expansion” permissiveness, per The Wall Street Journal • China import approvals for high-end accelerators, Watch whether the Hong Kong H200 inventory clears or stays stuck, and what categories get throttled, per Reuters • Memory roadmap moves, Watch whether “considering” becomes “committing” on 3D DRAM manufacturing and what timelines get implied, per The Information • Platform AI governance backlash, Watch whether bundling AI into mandatory surfaces triggers reversals or finer-grained controls, starting with schools, per The New York Times
The question heading into the week: Capital is concentrating. Permissioning is tightening. Interfaces are metering.
Which of these three moves first in your org?
Signal + Noise is strategic intelligence, not engagement-specific advice. For guidance calibrated to your org, start with Advisory.
…
Free with a Signal + Noise account
Create a free account to read the full weekly. No credit card required.
Sign up free to read the full weekly →