Yesterday's signals, distilled, A look back at September 15, 2026.
Capital kept moving up the stack.
OpenAI reportedly floated another private round at a $1.2T valuation ahead of an IPO. Factory raised $200M for coding agents that route across models. CADDi raised $114M to organize manufacturing’s engineering and production data. Profound raised $180M to sell brands visibility inside AI answers.
Different sectors. Same shape.
The market is underwriting “operating layers” more than it’s underwriting “models.” Orchestration, data normalization, and distribution surfaces are where durable margin and lock-in live, because they sit between the frontier and the workflow.
At the same time, the policy layer is getting less stable, not more. Senior political advisers meeting with Anthropic on AI safety is one signal. The public split between “slow down” and “accelerate” is another. For operators, this is less about ideology and more about procurement reality, release cadence, audit expectations, and contract language will diverge.
The strategic question to carry into this week: if your AI roadmap assumes a stable frontier supply and a stable regulatory posture, where do you have a fallback plan, and where are you accidentally building a single point of failure?
CAPITAL FLOWS / FRONTIER PLATFORM
Frontier AI is being priced like infrastructure, not software
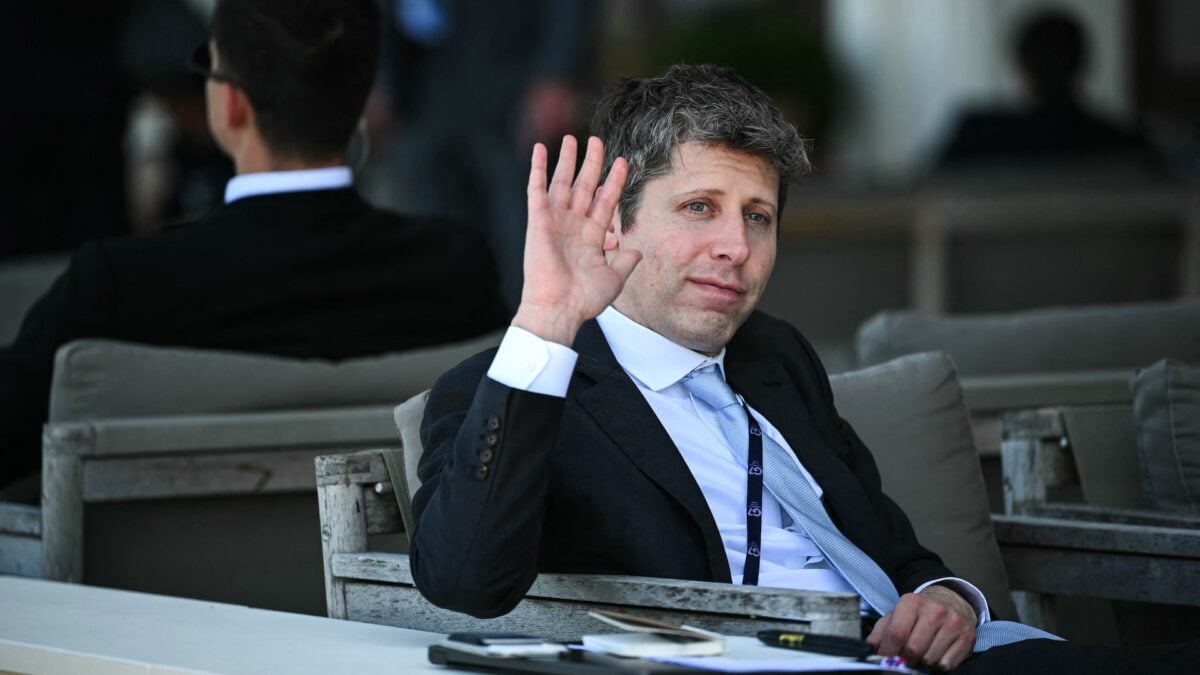
OpenAI explores another private round at a $1.2T valuation ahead of IPO
OpenAI has held early conversations with investors about raising another private funding round at a $1.2T valuation ahead of its planned IPO, per Financial Times.
The detail that matters isn’t the number as a flex. It’s what the number does to the rest of the market, because it implies a capital structure where frontier access, compute commitments, and distribution partnerships can be financed like a macro asset.
The Bet: Frontier model supply becomes a balance-sheet game, capital buys time, compute, and distribution while policy catches up.
So What? A $1.2T private-markets conversation is a signal that “frontier” is consolidating into a small set of capital-intensive platforms with the ability to set terms downstream. That pushes everyone else toward one of three defensible positions: (1) proprietary data and workflow ownership, (2) distribution you control, or (3) regulated-domain trust where audits and liability management are the product. If you’re an enterprise buyer, it also changes negotiating posture, your leverage won’t come from “we can switch models,” it will come from governance requirements, data residency, and integration depth.
The Risk: This is early-stage reporting, terms, timing, and even intent can change. And valuation gravity can create complacency inside customer orgs, assuming the biggest platform is automatically the safest operational choice.
Action:
- Inventory where your product or internal workflows are single-sourced to one frontier provider, log the switching cost in weeks, not in theory.
- Renegotiate AI vendor contracts around audit rights, incident disclosure, and data retention, treat it like critical infrastructure procurement.
- Set a quarterly “frontier dependency review” with engineering, security, and finance, model choice is now a capital and risk decision, not a dev preference.

BUILD / ENGINEERING
Orchestration is getting funded as the control plane for software creation
Factory raises $200M at a $5B valuation for model-switching coding agents
Factory raised $200M at a $5B valuation for its AI coding agents, called Droids, that switch between models depending on task complexity, per Wall Street Journal. The valuation was $1.5B in April.
This is a clean capital-market statement: the buyer isn’t betting on one model. They’re betting on routing, evaluation, and workflow integration as the durable layer.
The Bet: The winning developer stack is a broker, choosing models, tools, and policies per task, while presenting a single work surface to the team.
So What? Model-switching agents are a preview of how engineering orgs will actually consume frontier capability, through a governed orchestration layer that can optimize for cost, latency, and risk. That matters because it changes the unit of ownership: not “which model do we use,” but “who owns the agent policy, the eval suite, and the logs.” If a vendor owns that layer, you may get speed, but you also inherit lock-in around code provenance, security posture, and how quickly you can respond when a model behavior changes.
The Risk: The hard part isn’t generating code. It’s maintaining correctness under change, dependency updates, model updates, toolchain updates, and shifting internal standards. If the orchestration layer can’t produce reliable traceability, it becomes a scaling bottleneck disguised as productivity.
Action:
- Define what “agent traceability” means in your org, required logs, prompts/tool calls, model IDs, and review checkpoints, before you standardize on a vendor.
- Run a 2-week pilot on one bounded repo with explicit success criteria: PR throughput, defect rate, rollback frequency, and security findings.
- Decide who owns the agent policy layer, platform engineering, security, or dev productivity, and staff it like a real control plane.
INDUSTRIAL DATA / VERTICAL AI
Manufacturing’s data layer is being intermediated, fast
CADDi raises $114M Series D at a $1.2B valuation for manufacturing data organization
CADDi raised a $114M Series D at a $1.2B valuation for AI tools that help manufacturers organize engineering and production data, up from a $470M valuation in 2025, per Fortune.
This is not “AI in manufacturing” as a generic story. It’s the data substrate, BOMs, drawings, process specs, supplier history, being packaged into a product category.
The Bet: The company that normalizes engineering and production data becomes the default interface for automation, quoting, and supply-chain decisions.
So What? Manufacturing has always had AI potential, but it’s been gated by messy, fragmented, high-stakes data. A $1.2B valuation for a data-organization layer says the market believes the gating factor is finally being productized. For operators in heavy industry, the implication is uncomfortable but actionable: if you don’t build your own canonical engineering/production data layer, you will rent one, and the renter sets the schema, the integration points, and eventually the automation roadmap.
The Risk: Data normalization projects fail quietly, because the ROI is second-order and the org politics are first-order. If adoption stalls at “search and summaries,” the platform never becomes the system of record, and the promised automation never arrives.
Action:
- Map your engineering/production data sources this week, PLM, ERP, MES, QMS, supplier portals, and identify the current “source of truth” conflicts.
- Pick one workflow where data cleanliness is the bottleneck, quoting, change orders, nonconformance, and instrument it end-to-end.
- Require portability in any vendor evaluation, export formats, schema documentation, and clear offboarding terms, before you centralize critical manufacturing knowledge.

DISTRIBUTION / MARKETING SURFACES
“Answer visibility” is becoming a paid channel with its own vendors
Profound raises $180M at a $1.8B valuation to sell brands visibility in AI answers
Profound raised $180M at a $1.8B valuation to sell brands visibility in AI answers, positioned as “answer engine optimization,” per The Next Web.
This is a bet that assistants and answer engines are not just UX. They’re a new allocation of attention, and therefore budget.
The Bet: Brand distribution shifts from ranking pages to shaping model outputs, and the tooling becomes a standalone spend category.
So What? If marketing is still organized around search and social, you’re likely under-instrumented for the next surface where customers form preferences. The practical shift is measurement: you can’t manage what you can’t observe, and most orgs don’t have a baseline for “where do we show up in AI answers, and is it correct.” A vendor ecosystem forming here suggests the channel will professionalize quickly, dashboards, monitoring, content pipelines, and eventually paid placement dynamics.
The Risk: The space can devolve into vanity metrics, share-of-answer without conversion, or “visibility” that’s not tied to revenue. And platform policies can change faster than marketing orgs can adapt.
Action:
- Establish an “answer presence baseline” for your top 25 commercial queries, capture outputs, citations, and factual errors across the assistants your customers use.
- Assign ownership, marketing ops or growth engineering, for monitoring and remediation workflows when answers are wrong.
- Update your content pipeline to prioritize machine-citable assets, clear specs, pricing logic, policy pages, and authoritative docs that models can reference.
POLICY / GOVERNANCE
The speed debate is now procurement reality
Trump advisers meet with Anthropic executive over AI safety
Senior political advisers met with an Anthropic executive to discuss AI safety, per Bloomberg Technology.
This is a reminder that frontier model governance is being shaped through direct engagement with power centers, not just through formal rulemaking.
The Bet: Safety posture becomes a differentiator in how platforms are treated by policymakers, and in how enterprise buyers justify adoption.
So What? For operators, the immediate implication is contract and compliance drift. Some vendors will lean into audits, reporting, and controlled release cadences. Others will optimize for speed and capability shipping. That divergence will show up in procurement checklists, insurance conversations, and board-level risk tolerance. If you’re deploying high-capability systems in sensitive workflows, you need to know which posture your vendor is implicitly choosing, because you inherit it.
The Risk: Political attention can create volatility without clarity, more meetings, more statements, but not necessarily stable rules. That can freeze deployments if internal stakeholders wait for certainty that never arrives.
Action:
- Add a “policy posture” section to vendor due diligence, release cadence, audit commitments, incident disclosure norms, and escalation paths.
- Pre-brief legal and compliance on your highest-risk AI workflows, so you can move with a documented rationale when scrutiny increases.
- Build a lightweight internal standard for model changes, what triggers re-evaluation, who signs off, and what gets logged.
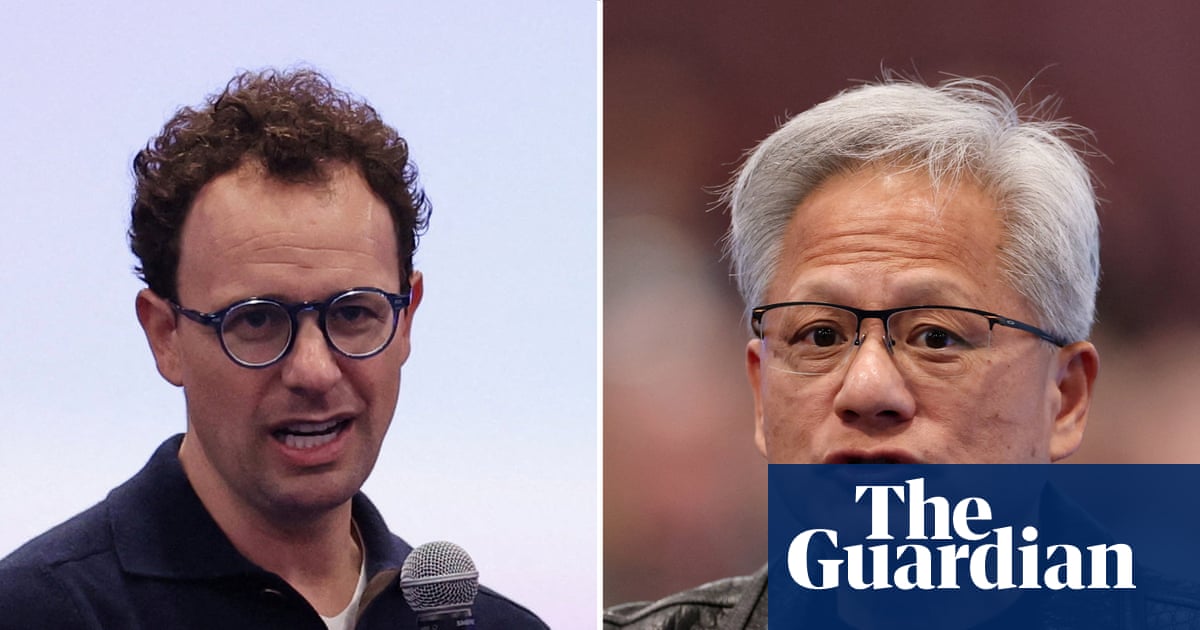
Anthropic CEO calls for slowdown as Nvidia urges acceleration
Dario Amodei renewed calls for slowing AI development while Jensen Huang argued for acceleration, per The Guardian.
This isn’t a debate to spectate. It’s a signal that “pace” will be embedded in product defaults, guardrails, access tiers, and what gets shipped when.
So What? If you’re a buyer, you should expect different operational profiles: one path optimizes for maximum capability and rapid iteration; the other optimizes for controlled deployment and governance. Neither is universally correct. But pretending they’re interchangeable is how you end up with a mismatch between your risk tolerance and your vendor’s incentives.
Action:
- Classify your AI use cases into “speed-sensitive” vs “liability-sensitive” and align vendor selection accordingly.
- Ask vendors for their last 3 model-change incident notes or behavior-change disclosures, if they can’t produce them, assume you’re flying blind.
CONTRARIAN SIGNAL
The real consolidation isn’t models. It’s budgets.
Most people read yesterday’s funding as “AI is hot again.”
A better read is that budgets are being re-labeled and re-routed into new control points: engineering spend into agent orchestration, industrial spend into data normalization, marketing spend into answer visibility, and balance-sheet capital into frontier platforms.
That’s consolidation, just not the kind that shows up as one company buying another. It shows up as fewer places where decisions get made, and more of your organization’s output flowing through those places.
The Takeaway: If you don’t name your control points, you will rent them by default.
THE QUESTION FOR TODAY
Frontier platforms are being financed like infrastructure. Engineering is being reorganized around orchestration layers. Industrial AI is being won by whoever owns the canonical data substrate. Marketing is being pulled toward answer surfaces you don’t fully measure yet. Policy posture is diverging, and you inherit it through your vendors.
Where are you still making “tool choices” when you should be making “control-plane choices”?
Signal + Noise is strategic intelligence, not engagement-specific advice. For guidance calibrated to your org, start with Advisory.
See exactly how this impacts your specific industry and function. Upgrade to PRO to get bespoke tactical breakdowns generated instantly for your operating model.
Go deeper with the Weekly Signal
This is the daily take. The Weekly goes further — full strategic analysis across 8–10 sections, each with a signal read and operator action items. Source panel included.
Sign up free → then upgrade